The short version
Declare a medical condition and many travel insurers refuse you, exclude it or hike the price. The Equality Act says they need relevant, reliable evidence to do that, and FCA rules say they must point you to specialist cover. Here's how to insure yourself, and your wheelchair, without being fleeced.
You tick “yes” to the medical question, and the quote vanishes. Or it comes back with your condition excluded, or at a price that makes you wince. For many disabled people, travel insurance is where the holiday starts to fall apart, long before anyone reaches the airport.
Insurers are allowed to treat you differently. But only on evidence, only when it’s reasonable, and only if they then point you towards someone who will cover you. The law is on your side more than the quote screen suggests. Here’s how to use it.
Declare everything: the question you can’t afford to fudge
Under the Consumer Insurance (Disclosure and Representations) Act 2012, you have a legal duty to “take reasonable care not to make a misrepresentation to the insurer”. In practice, that means answering the medical questions honestly and fully. You don’t have to volunteer things they never asked about. But a careless or wrong answer lets the insurer cut or refuse a claim. That could leave you with a hospital bill abroad running into thousands.
Being disabled doesn’t automatically mean you have a “medical condition” to declare. It depends on the exact wording. Some questions ask about treatment, some about prescriptions, and some about tests you’re still waiting for.
- Have your repeat prescription list to hand. Medications remind you of conditions you’d forgotten to mention.
- Include things you’re waiting on. Pending tests and referrals are often asked about separately.
- If a question is unclear, ring and ask. Note the date, the time and what you were told.
- Tell them about changes before you travel. Policies usually require you to report a new diagnosis or medication.
The Equality Act exception, and what it doesn’t allow
Insurance gets its own carve-out in the Equality Act 2010. Schedule 3, Part 5, paragraph 21 says an insurer isn’t discriminating against a disabled person if what it does is:
- done by reference to information that is relevant to assessing the risk being insured, and
- from a source it is reasonable to rely on, and
- reasonable in itself.
All three must be true. A blanket “we don’t cover wheelchair users” is on much weaker ground. So is a loading for a condition with no link to your risk of claiming.
Make them show their workings
If you’re refused, or the price seems wildly out of line, write to the insurer. Ask for the reason for the decision, the information it relied on, and why acting on it is reasonable in your case. You can also make a free subject access request for the personal data the insurer holds about you. A vague reply is a good basis for a complaint.
For free discrimination advice in England, Scotland or Wales, call the Equality Advisory and Support Service on 0808 800 0082. The Equality Act doesn’t cover Northern Ireland. There, the older Disability Discrimination Act 1995 applies, and the Equality Commission for Northern Ireland can advise.
Refused, excluded or loaded? The rule that sends you somewhere better
Since April 2021, Financial Conduct Authority (FCA) rules have required travel insurers to signpost you to a specialist directory if, because of a medical condition, they refuse to quote, exclude the condition, or add a large amount to your premium.
That last trigger changed on 1 January 2026. It used to be £100 extra because of your condition. It’s now £200, and it will be updated every five years in line with inflation. So a £150 loading no longer has to come with a signpost. Don’t wait to be told.
The FCA recognises two directories: the government-backed MoneyHelper travel insurance directory and the British Insurance Brokers’ Association (BIBA) travel medical directory. Both list firms that specialise in serious pre-existing conditions. A specialist broker can also shop around for you, so you only explain your medical history once.
A refusal from one insurer is not a verdict on whether you can travel. It’s a sign you’ve been talking to the wrong insurer.
GHIC: useful, free, and not travel insurance
The UK Global Health Insurance Card (GHIC) is free and lasts up to five years. It gives you medically necessary state healthcare in the EU and some other countries on the same terms as local residents. That includes care for a chronic condition. Apply only through the official NHS site, because unofficial sites charge a fee. Treatment such as kidney dialysis or chemotherapy must be arranged in advance.
| Situation | GHIC / EHIC | Travel insurance (if declared) |
|---|---|---|
| Emergency state hospital treatment | Yes, on local terms. You may still have to pay a charge | Yes |
| Chronic condition care that can’t wait until you’re home | Yes | Usually, if accepted |
| Private hospital treatment | No | Often |
| Medical repatriation to the UK | Never | Usually |
| Mountain rescue | No | Depends on the policy |
| Cancellation, or damaged equipment | No | Depends on the policy and its limits |
Your wheelchair in the hold: the gap nobody mentions
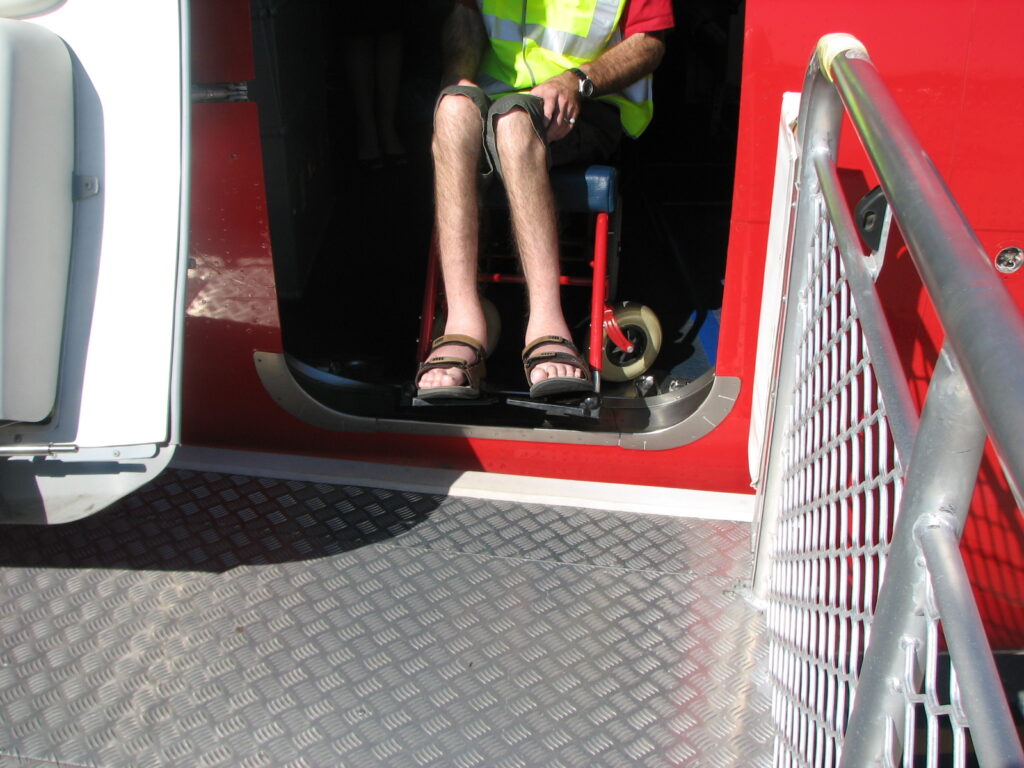
The Civil Aviation Authority (CAA) collected figures from 13 large airlines. They carried 282,947 wheelchairs to and from the UK in 2023. Among the airlines that could report damage, an average of 0.43% were damaged. That sounds small, until the broken chair is yours.
On international flights, the Montreal Convention caps an airline’s liability for damaged, lost or delayed baggage, including mobility equipment, at 1,519 Special Drawing Rights. That’s an International Monetary Fund currency unit. The CAA valued the cap at about £1,544 in August 2025, and a powered wheelchair can cost many times that. You can raise the cap by making a “special declaration of interest” at check-in, though the CAA says passengers rarely do.
The CAA encourages airlines to cover the full cost voluntarily, and some say they will pay above the cap. It also consulted in late 2025 on making airlines publish damage figures. As of September 2026, no decision has been published and the cap is unchanged. The gap is yours to insure.
- Check your travel policy’s single-item limit. It may be far below what your powerchair is worth.
- Check your home contents policy. Some cover items away from home. Others exclude mobility equipment or transit damage.
- Consider specialist wheelchair or scooter insurance. Ask whether it covers damage while an airline, ferry or coach is carrying it.
- If your chair is on loan from the NHS wheelchair service, ask what you’re responsible for before you fly.
If it comes back damaged, report it before you leave the airport. Then complain to the airline in writing. Under the Montreal Convention, you have just seven days from getting damaged checked baggage back. Our guide to flying while disabled covers the airport process, and the CAA has guidance on travelling with mobility equipment.
Before you buy: a checklist
- Gather your prescription list, and details of any pending tests or referrals.
- Answer every screening question accurately, and screenshot your answers.
- If you’re refused, excluded, or charged over £200 extra because of a condition, use the MoneyHelper or BIBA directory, or a specialist broker.
- Ask any insurer that refuses you what information its decision was based on. Do it in writing.
- Compare the limits for medical costs, repatriation, cancellation and single items with what you’d actually need.
- Insure your wheelchair or scooter separately if the policy won’t cover its full value in transit.
- Get your free GHIC, and pre-arrange any treatment such as dialysis.
When it goes wrong: complaining to the Ombudsman
Rejected claim? Unexplained exclusion? A price that makes no sense? Complain to the insurer first, in writing, and call it a formal complaint. Our complaint template will help. Most firms then have up to eight weeks to send a final response.
If you’re still unhappy, or eight weeks pass without a reply, go to the Financial Ombudsman Service. It’s free, and its helpline is 0800 023 4567. You must bring your complaint within six months of the insurer’s final response. If your disability drove the decision, say so, and point to the Equality Act test and the FCA signposting rule.
You have the same right to travel as anyone else, and the right to be priced on evidence, not assumption. Declare honestly, make insurers justify their decisions, and use the directories they have to point you to. Then book the trip, abroad or on one of our accessible UK breaks.